
MoBill Budget and Reminder
- Rating
- 4.0
- Downloads
- 500.00K
- Content Rating
- Everyone
MoBill Budget and Reminder - Screenshots
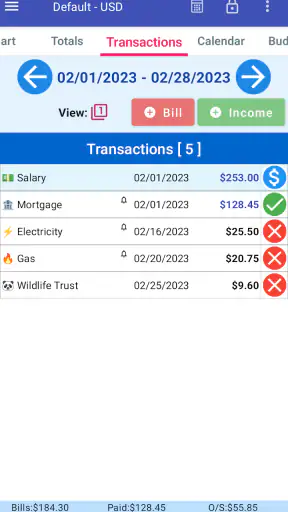
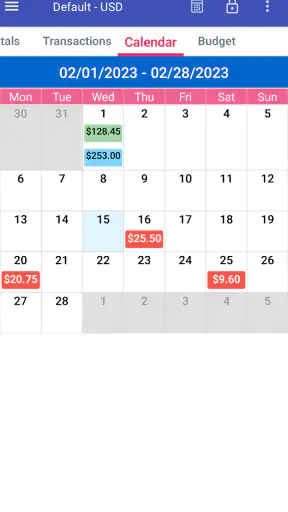
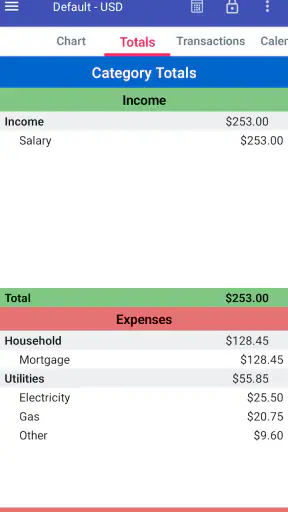
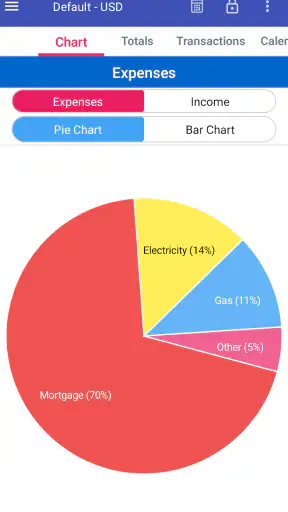
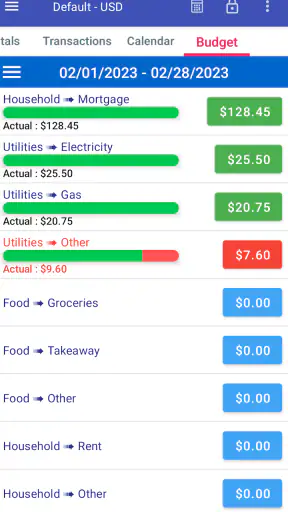
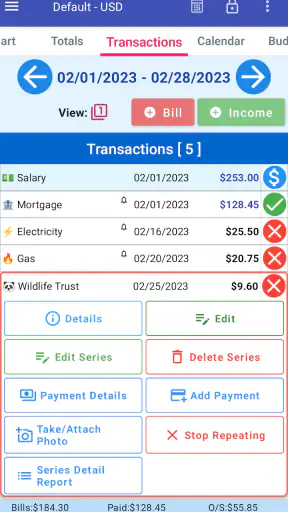
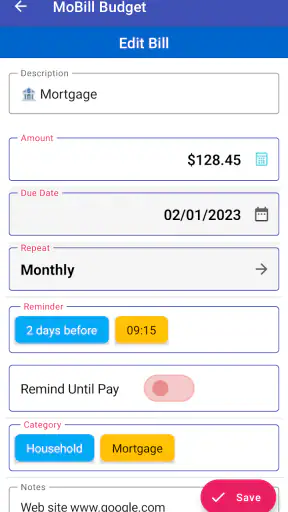
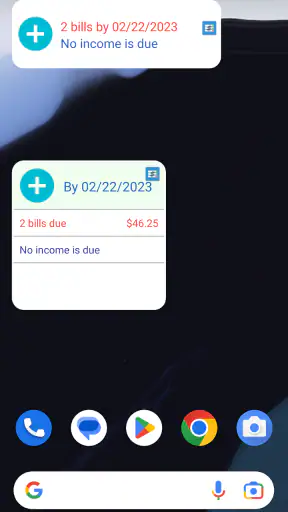
Pros
- Simple interface makes tracking bills and spending easy.
- Payment reminders help reduce the risk of missed due dates.
- Useful budgeting tools for organizing recurring expenses.
- Quick expense entry keeps daily financial updates convenient.
- Can improve awareness of monthly cash flow and spending habits.
Cons
- Some advanced features may require a paid upgrade.
- Manual data entry can become time-consuming for frequent transactions.
- Limited bank integration may require checking accounts separately.
- Reminder reliability can depend on notification permissions.
- May feel too basic for users needing detailed financial reports.
MoBill Budget and Reminder - Description
- App Name
- MoBill Budget and Reminder
- Package Name
- com.mobill.app
- Developer
- MoBill Apps
- Category
- Finance
- Last Updated
- Feb 28, 2011
- Version
- 5.3.1
Managing money is rarely difficult because of one huge expense. It is usually the small, repeated decisions that cause trouble: a bill that slips past, a subscription that renews at the wrong time, or a budget that exists only in your head. MoBill Budget and Reminder takes a straightforward approach to that problem. It is a finance app from MoBill Apps, focused on keeping personal spending plans and payment reminders in one place rather than trying to become a full banking service.
I found its appeal easiest to understand when looking at ordinary routines. You can use it as a personal checkpoint before payday, a reminder system for recurring obligations, or a simple way to see whether your spending is moving away from the limits you set. It is not the sort of app I would recommend to someone who wants investment analysis, bank synchronization, or a highly visual financial dashboard. Its value is more practical: it encourages you to remember what is due and pay attention to where your money is going.
The app is free to install, with optional in-app purchases priced from $2.50 to $10.99 per item. That distinction matters. You can try the basic experience without committing money, while the paid options provide a way to decide whether extra value is worth paying for after you understand the workflow. I appreciate that arrangement because a budgeting tool needs to fit personal habits; no description can tell you in advance whether its style will feel natural.
How MoBill fits into everyday money management
A focused tool rather than a complete financial command center
MoBill Budget and Reminder sits in the personal finance category, but I would place it toward the practical, hands-on end of that category. Instead of asking you to hand over your entire financial life to an automated system, it works best when you deliberately enter and review the information that matters to you. That can be a strength for people who want control and a weakness for anyone expecting instant account-wide analysis.
The distinction between a budget and a reminder is important here. A budget answers, “How much can I reasonably spend?” A reminder answers, “What must I remember before the due date?” Combining both ideas makes sense because a bill is not only a calendar event; it also affects the amount available for everything else. When I think about the app in that context, its most useful role is helping connect planned obligations with day-to-day spending decisions.
A realistic example is a household that receives income near the start of the month but has several payments scattered across the following weeks. Rather than relying on a paper note or a vague memory, the user can keep those obligations visible and check the budget before making optional purchases. The benefit is not dramatic automation. It is the quiet reduction of avoidable surprises.
What the free starting point means
The free entry point makes sense for cautious users. You can install the app and decide whether entering your financial details manually is worth the effort before considering an optional purchase. That is especially useful if you are moving away from a notebook or a basic phone reminder and are unsure whether a dedicated finance app will become part of your routine.
I would not treat the word “free” as a promise that every possible convenience is included. The presence of optional purchases means the experience may have extra paid value depending on what you need. The sensible approach is to use the free version long enough to test three things: whether the input process feels quick enough, whether the reminder approach matches your schedule, and whether reviewing the budget actually changes your decisions.
That trial period also protects you from a common budgeting mistake: paying for a sophisticated tool before developing the habit of checking it. A premium feature cannot compensate for an app that you forget to open. In my view, MoBill is better evaluated by consistency than by the number of options it presents.
Where the app delivers practical value
The strongest value comes from bringing two behaviors together. First, you record the financial commitments that need attention. Second, you use that information when deciding what is safe to spend. Many ordinary alternatives handle only one side: a calendar can remind you about a date, while a spreadsheet can show calculations. MoBill’s positioning is useful because it keeps the reminder and budgeting mindset close together.
It can also suit people who prefer deliberate control over automatic imports. Manual involvement takes more effort, but it can make you more aware of each recurring obligation. For someone trying to understand why a monthly plan keeps failing, that awareness is valuable. Entering a payment is not just clerical work; it forces you to acknowledge the commitment before treating the remaining balance as available money.
Another useful workflow is a weekly review rather than constant checking. I would use a short session to look ahead at upcoming bills, compare them with the current plan, and adjust discretionary spending if necessary. This avoids turning personal finance into an exhausting daily task. The app becomes a prompt for a repeatable habit instead of another source of notifications that you ignore.
Three details that affect the experience more than they first appear
The quality of your reminders depends on the quality of your setup. A reminder that is too early may become background noise, while one that appears too late does not leave enough time to act. I would set reminders around the point when I can still move money, change a payment method, or contact a provider. The best schedule is not necessarily the official due date; it is the date that gives you a realistic opportunity to respond.
A second insight is that a budget should include irregular pressure, not only predictable monthly bills. Annual renewals, seasonal costs, and occasional household expenses can make a plan look healthy until they arrive. Even if you use MoBill mainly for recurring payments, reviewing less frequent obligations alongside the normal monthly picture can prevent false confidence. The app is most helpful when it supports honest planning rather than an artificially tidy budget.
Third, the app can be used as a decision filter before spending, not merely as a record after spending. Before making a nonessential purchase, I would check what is due before the next income cycle and leave room for those commitments. This is a small change in behavior, but it is more useful than entering expenses only after the money has already disappeared.
How it compares with familiar alternatives
A spreadsheet remains better for people who enjoy building custom formulas, detailed categories, and long-term reports. It can be shaped around almost any financial system, but it also demands maintenance and does not automatically become a convenient reminder tool. MoBill is the more approachable choice when the priority is a ready-made personal workflow rather than designing your own accounting model.
A standard calendar is stronger for general scheduling and shared household events, but it does not naturally connect a payment date with a spending plan. You might remember the bill and still forget its effect on the rest of the month. MoBill’s finance focus gives that reminder more context.
Banking apps can be preferable for users who want transactions pulled directly from their accounts or who need official account balances in one place. They may reduce manual entry, although they can also feel excessive for someone who wants a small, private budgeting routine. I would choose MoBill over a banking app when I want a separate planning layer, but I would not expect it to replace the bank’s authoritative transaction record.
Dedicated subscription trackers may be a better fit if recurring services are your only concern. MoBill makes more sense when reminders are part of a broader personal budget, including ordinary bills and spending limits. The right choice depends on whether your problem is one narrow category or the relationship between several obligations.
Where the trade-offs become noticeable
The main trade-off is the balance between control and convenience. A hands-on finance tool can make you more aware of your money, but it asks you to keep information current. If you stop updating entries, the plan becomes less trustworthy. This is not a flaw unique to MoBill, but it is particularly important when choosing an app that is centered on intentional input rather than effortless background collection.
There is also a difference between a reminder and a guarantee. A notification can prompt action, but it cannot ensure that a payment succeeds, that an account has enough funds, or that a provider has not changed its schedule. I would treat MoBill as a planning aid and still verify important transactions through the relevant financial service. That separation keeps expectations realistic.
Users who want polished visual analytics may find the focused approach limiting. If your motivation depends on charts, detailed trend comparisons, or extensive reporting, a more specialized budgeting platform may hold your attention better. Likewise, people managing multiple accounts, shared finances, investments, or business expenses should think carefully before making this their only financial tool.
The optional purchase model is another point to consider. The app costs nothing to start, but paid items can range from $2.50 to $10.99. I would judge those purchases by a simple question: do they remove a repeated annoyance or improve a routine I already use? Paying for features before establishing that routine would not be good value for me.
Who is most likely to benefit
MoBill is a good candidate for someone who has missed bills because reminders are scattered across notes, calendars, and memory. It also suits a person beginning to budget for the first time and looking for something less intimidating than a full financial management suite. The Everyone age rating makes it broadly approachable, although the useful audience is really defined by financial habits rather than age.
It may be especially helpful during a transition: moving into a new home, taking responsibility for household bills, changing income patterns, or trying to stop relying on end-of-month guesswork. In those situations, the combination of planning and reminders gives you a simple structure while you learn which expenses deserve regular attention.
I would also recommend trying it to someone who dislikes linking financial accounts. Manual entry is a burden for some people, but for others it is a boundary they actively want. Keeping a planning tool separate from banking access can make the process feel more intentional and easier to understand.
On the other hand, I would suggest skipping it as a primary solution if you need automatic transaction imports, investment tracking, shared real-time household access, or formal accounting records. A spreadsheet, banking tool, or more advanced finance platform may be better in those cases. MoBill should not be stretched into a role it was not designed to fill.
What to know before installing
The app was released on February 28, 2011, and the current version is 5.3.1. It requires Android 8.0 or later, so compatibility is worth checking on an older device before planning to use it as your main reminder system. The long presence of the app can be reassuring for someone who prefers an established utility, but I would still evaluate the current experience on your own phone rather than assuming age alone guarantees a perfect fit.
Its audience is substantial, with over 500 thousand installs, alongside a 4.0 average from around 3.8 thousand ratings and roughly 1.6 thousand written reviews. Those figures suggest that many people find the concept useful, while also leaving room for individual differences in expectations. I would read that overall reception as encouragement to try it, not as a reason to ignore the limitations of a manually maintained budget.
Before relying on it for an important payment, I would perform a small test. Add one ordinary bill, choose a reminder point that gives you time to act, and check whether the notification fits naturally into your day. Then review whether the entry helps you make a spending decision. This test answers more than a quick installation because it evaluates the whole loop from setup to action.
My value verdict
MoBill Budget and Reminder offers its best value when you want a simple, deliberate system for bills and personal budgeting without paying before you know it fits. The free starting point lowers the risk, and the optional purchases give committed users a way to consider additional value after testing the basics. I would not buy anything immediately; I would first build a small routine and see whether the app genuinely prevents missed obligations or improves spending choices.
For me, the deciding advantage is its practical focus. It does not need to replace a bank, spreadsheet, calendar, and investment service all at once to be useful. As a companion for planning upcoming commitments and keeping a budget visible, it has a clear purpose. The cost is the attention required to keep the information accurate, and that cost is acceptable only if you are willing to maintain the habit.
My recommendation is to try it if your financial problem is disorganization, forgotten bills, or a lack of connection between payment dates and spending decisions. I would skip it if you want automation, advanced analysis, or a complete financial command center. For the right user, MoBill Budget and Reminder is a sensible free experiment with optional paid value; for everyone else, its hands-on style may feel like extra work rather than relief.
FAQ
What is MoBill Budget and Reminder used for?
MoBill Budget and Reminder is designed to help you organize personal finances by recording income, expenses, bills, and payment reminders in one place. After reviewing its main functions, it appears most useful for people who want a simple overview of recurring payments and everyday spending, rather than a complex investment or accounting platform.
Can I use MoBill Budget and Reminder to track recurring bills and payment dates?
Yes, recurring bills and reminders are among the app’s most practical features. You can record regular obligations such as rent, utilities, subscriptions, loans, or insurance and set dates to help avoid missed payments. However, users should still check whether notifications are enabled on their device, since battery-saving settings or disabled permissions can affect reminder delivery.
Does MoBill Budget and Reminder connect directly to my bank account?
MoBill Budget and Reminder is primarily intended for manually organizing financial information, so users should not assume that it automatically imports transactions from their bank. This can be an advantage for privacy and control, but it also means that keeping the information accurate requires regular updates. Check the current app listing for any supported synchronization features.
Is MoBill Budget and Reminder free to download and use?
The app may be available to download without an upfront charge, but pricing can depend on the platform, version, and any premium features offered by the developer. Before installing or subscribing, review the Google Play Store or App Store listing carefully for in-app purchases, advertisements, trial conditions, and renewal terms, as these details may change over time.
Is MoBill Budget and Reminder suitable for beginners?
MoBill Budget and Reminder should be approachable for beginners who mainly need a straightforward way to list expenses, manage bills, and receive reminders. The app is less intimidating than a full financial management suite, although its usefulness depends on entering information consistently. Users looking for shared household accounts, advanced reports, or professional bookkeeping tools may need a more specialized application.


